As the year winds down, it’s easy to feel like there’s no time left to make a meaningful impact on your tax situation. But don’t worry—there are still last-minute moves you can make to maximize deductions, reduce your taxable income, and set yourself up for a stronger financial start in the new year. From charitable contributions to retirement account contributions, a few smart actions now can translate into significant savings come tax season. In this final blog of the year, we’ll share quick, actionable tax tips you can implement just in the nick of time.
Set aside time to plan
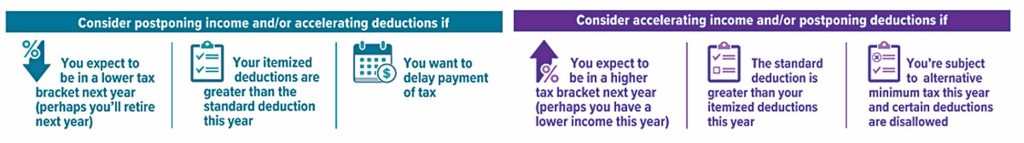
Effective planning requires that you have a good understanding of your current tax situation, as well as a reasonable estimate of how your circumstances might change next year. There’s a real opportunity for tax savings if you’ll be paying taxes at a lower rate in one year than in the other. However, the window for most tax-saving moves closes on December 31, so don’t procrastinate.
Defer income to next year
Consider opportunities to defer income to 2025, particularly if you think you may be in a lower tax bracket then. For example, you may be able to defer a year-end bonus or delay the collection of business debts, rents, and payments for services in order to postpone payment of tax on the income until next year.
Accelerate deductions
Look for opportunities to accelerate deductions into the current tax year. If you itemize deductions, making payments for deductible expenses such as qualifying interest, state taxes, and medical expenses before the end of the year (instead of paying them in early 2025) could make a difference on your 2024 return.
Make deductible charitable contributions
If you itemize deductions on your federal income tax return, you can generally deduct charitable contributions, but the deduction is limited to 50% (currently increased to 60% for cash contributions to public charities), 30%, or 20% of your adjusted gross income, depending on the type of property you give and the type of organization to which you contribute. (Excess amounts can be carried over for up to five years.)
Increase withholding
If it looks as though you’re going to owe federal income tax for the year, consider increasing your withholding on Form W-4 for the remainder of the year to cover the shortfall. The biggest advantage in doing so is that withholding is considered as having been paid evenly throughout the year instead of when the dollars are actually taken from your paycheck.
More to Consider
Here are some other things to consider as part of your year-end tax review.
Save more for retirement
Deductible contributions to a traditional IRA and pretax contributions to an employer-sponsored retirement plan such as a 401(k) can help reduce your 2024 taxable income. If you haven’t already contributed up to the maximum amount allowed, consider doing so. For 2024, you can contribute up to $23,000 to a 401(k) plan ($30,500 if you’re age 50 or older) and up to $7,000 to traditional and Roth IRAs combined ($8,000 if you’re age 50 or older). The window to make 2024 contributions to an employer plan generally closes at the end of the year, while you have until April 15, 2025, to make 2024 IRA contributions. (Roth contributions are not deductible, but qualified Roth distributions are not taxable.)
Take any required distributions
If you are age 73 or older, you generally must take required minimum distributions (RMDs) from your traditional IRAs and employer-sponsored retirement plans (an exception may apply if you’re still working for the employer sponsoring the plan). Take any distributions by the date required — the end of the year for most individuals. The penalty for failing to do so is substantial: 25% of any amount that you failed to distribute as required (10% if corrected in a timely manner). Beneficiaries are generally required to take annual distributions from inherited retirement accounts (and under certain circumstances, a distribution of the entire account 10 years after certain events, such as the death of the IRA owner or the beneficiary); there are special rules for spouses.
Weigh year-end investment moves
Though you shouldn’t let tax considerations drive your investment decisions, it’s worth considering the tax implications of any year-end investment moves. For example, if you have realized net capital gains from selling securities at a profit, you might avoid being taxed on some or all of those gains by selling losing positions. Any losses above the amount of your gains can be used to offset up to $3,000 of ordinary income ($1,500 if your filing status is married filing separately) or carried forward to reduce your taxes in future years.
As the clock ticks down on the year, taking a few moments for last-minute tax-saving strategies can make a big difference. Whether it’s maximizing deductions, contributing to retirement accounts, or making charitable donations, these actions can help reduce your tax burden and position you for financial success. However, don’t stop there—use this time as an opportunity to start planning for next year. Setting aside time to evaluate your financial goals, review potential investment strategies, and build a tax-efficient plan for the year ahead will ensure you’re prepared well before the next deadline approaches. With a little proactive effort now, you’ll be able to close out this year confidently and step into the next one ready for success.

Sources: Broadridge Investment Management Solutions
Stone Oak Wealth is regulated by the SEC as a registered investment adviser. Please see visit Legal Disclosures for additional advertising disclosures.
Stone Oak Wealth Management does not provide tax advice and a qualified tax accountant should be consulted.